June 2008
In June 2008 southern Wisconsin took prolonged heavy rain onto ground that was already saturated. The preceding winter had brought over a hundred inches of snow in places, an August 2007 flood had left the region wet, and spring had been damp. There was nowhere for the rain to go.
The Rock River rose to a level not seen in living memory. Communities along it — Fort Atkinson, Janesville, Afton, Beloit — saw sustained flooding rather than a flash event, and the USGS published a full study of the episode afterwards. Basements filled across the low-lying parts of the county, and in the river neighborhoods they filled on properties where no rain had fallen on the lot in any meaningful quantity.
Have a specific situation?
This article covers the general case. For your own building, call and describe what you are seeing. The conversation is free.
(608) 724-1919Free phone consultation.
The Flood Was Not the Problem
This is the part worth understanding sixteen years later. The flood was an event with a beginning and an end. What has lasted is what happened in the eight weeks afterwards, in houses that were pumped out, dried with fans, and put back together.
River flood water is Category 3 in the restoration classification — biologically contaminated, because it has been in contact with soil, agricultural runoff, road surfaces and frequently sewage. The rule for Category 3 is simple and it is not a matter of judgment: porous material that has been in it is removed. Drywall, insulation, carpet, pad, ceiling tile, particleboard. All of it, regardless of how dry it subsequently feels.
What happened instead, in a great many properties, is understandable. People pumped the water out, ran fans for a week or two, found the surfaces dry to the touch, and closed the walls back up. The drywall looked fine. The insulation looked fine. Nobody had told them that "dry" was not the test.
A persistent musty smell in a basement that no amount of dehumidification resolves. Allergy symptoms that improve when the household is away. A finished basement that has been repainted and still smells. No visible growth anywhere, because the growth is on the concealed face of the board and along the bottom plate. If a property took river water and nobody opened the walls, that is the most useful single fact you can give a specialist on the phone.
Why the Smell Is the Only Symptom
Growth on the back of drywall produces nothing visible on the room side for a very long time. The paper facing you can see stays dry; the paper facing you cannot see is the one that was wet. So the wall looks sound, paint holds, and the only thing that escapes into the room is odor — which people habituate to and stop noticing in their own house, which is why visitors comment on it and residents do not.
It Is Not Only About Floods
The extreme event gets the attention, but the ordinary version is more common and affects more properties. On the low ground — Blackbridge, Riverside, Traxler Park, downtown, Afton — the water table follows the Rock River within days. The river rises because of rain across a large catchment upstream, and a few days later groundwater comes up through the slab joint and the sump pit on a property where nothing has happened locally at all.
Owners describe basements taking water on a clear afternoon and are sometimes not believed. They are describing exactly what occurred.
What to Do If You Take Water Now
- Electricity off to the affected areaBefore anything else, if there is standing water near outlets or appliances.
- Photograph everything before moving itThis matters for insurance more than anything else you do that day.
- ExtractPump or wet vacuum. Every hour counts against the 24 to 48 hour window.
- Remove porous material, do not dry itIf the water came from the river, this is not a judgment call. Cut drywall above the water line, take out insulation and carpet pad, bag it.
- Then dry the structureAir movement and dehumidification, to documented moisture readings rather than to the feel of it.
- Verify before rebuildingIndependent clearance while the walls are still open.
Insurance: The Distinction That Catches People
A standard Wisconsin homeowners policy covers sudden and accidental water — a burst supply line, an appliance failure. It excludes surface flooding and rising groundwater. River water is flood, and flood requires a separate NFIP policy or a private flood product.
This is exactly where Rock River properties get caught: the water that entered came from the river rather than from anything that failed inside the house, so the homeowners policy does not respond. A burst pipe in the same basement would usually be covered. If you are on low ground near the Rock, the worthwhile action is not to assume — check which policy you actually hold.
Questions This Article Raises Most Often
Yes, and it is the most common hidden cause in the river neighborhoods. River water is Category 3, so porous material that was in it should have been removed rather than dried. Where it was left in place it will have colonized on the concealed face, and the only symptom that reaches the room is smell. The check is straightforward: a moisture and inspection survey, with a small opening in the wall at the level the water reached. If the wall is clean, you have your answer cheaply.
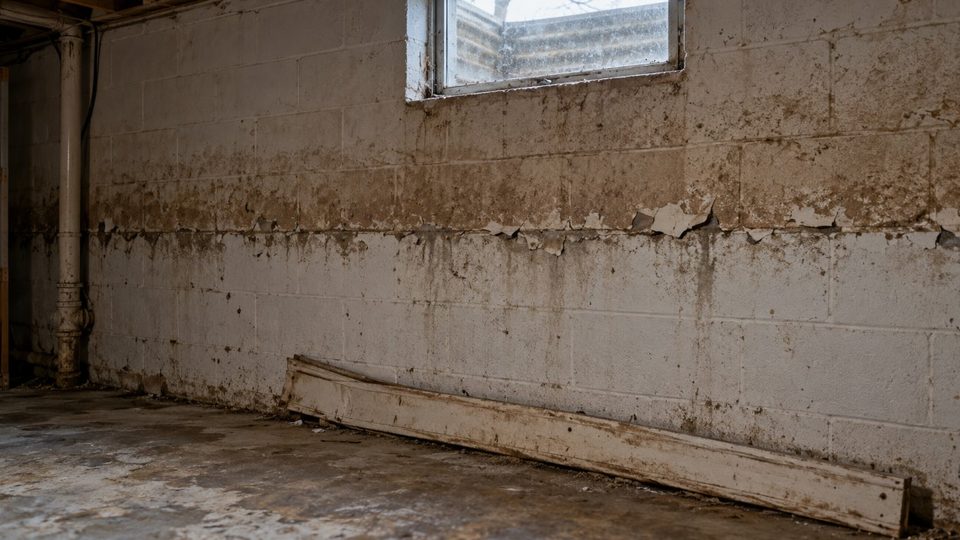
Several traces usually survive. A faint horizontal tide line on masonry. Efflorescence in a band. A change in the paint or the appearance of the drywall at a consistent height. Rust lines on metal shelving or on the water heater. Warping at the base of trim or door casings. If the finishes have since been replaced, neighbors, the previous owner, and city or county flood records for the event are worth asking.
On the low ground near the river, groundwater rising into the basement most springs is a realistic expectation rather than a worst case. A repeat of 2008 is a different question and is a genuinely rare event. What changes the outcome either way is the same: a sump sized to the actual recovery rate of the pit, a second pump on a higher float, a battery or water-powered backup, a check valve on the floor drain, nothing porous stored on the slab, and flood insurance if the property is in a flood zone.
Extraction, removal of wet material and structural drying typically runs $2,500 to $8,000 in this market, before any mold remediation or reconstruction. If material was left in place after a previous event and now needs removing, it is priced as a remediation rather than an emergency — a finished basement runs $4,000 to $12,000 excluding rebuilding. The advantage of dealing with an old problem is that it is not urgent, so it can be planned and quoted properly.
NFIP policies provide limited coverage for mold damage where it results directly from the flood and where the policyholder took reasonable steps to prevent it — which in practice means acting promptly once access was possible. Coverage is narrower than people expect and the documentation requirements are real. Photograph everything before moving it, keep receipts for mitigation, and report promptly. Delay is the most common reason a payable claim gets reduced.